thanks very much and uh thanks for the invitation I'm very pleased to be here um so this title is a bit broad what I will uh be talking about mainly uh comes from three uh papers one paper is has been published within the IMF working paper series about a year ago and then there are two draft papers that were shared I think uh at least to the discussions and I think there are a prolongation of uh uh of the first one in in different specific dimensions um and B maybe but for those of you who
uh read French uh this refers also to this book uh that was out in the first quarter this year uh uh written with Michelle ageta so in this book we we have very ambitious uh and wide- ranging goal which is to re explain the different phases of capitalism with uh the lens of uh political ecology uh with three big Parts in it one is a bit uh conceptual or or political philosophy if you if if you want um trying to Define what what we call uh um uh the the sorry because I'm not used to
speak about this book in in in English so I I don't find the world but but basically different phases of uh historical viability um and then the the core part uh like revisits uh these different phases uh in the in the long uh long uh time period long history and we have last section uh which is much more about now and what happens uh what's the current situation in the um different variability phases of capitalism um and and which basically retakes some of those arguments that are in this uh IMF working paper and goes a
bit uh Beyond uh also giving the example of France as a case study um so let me uh let me first uh highlight the motivation of this uh last year IMF paper that's that tries to basically defines uh what's uh what's the political moment for uh mitigation policies and and and transition policies uh by putting the emphasis on two Dimensions the crossborder dimension and the notion of meid transition um so the motivation is that uh the transition uh has been very much thoughts at the global level or at the national level but not too much
as uh a potential shift in the relations between countries on trade side on the economic side social side financial side uh but because of this uh uh huge globalization Trend that we we have experienced in the past decades uh this uh crossborder Dimension is essential to understand what could be the drivers of accelerated transition or on the contrary uh potential uh bottlenecks or or uh political issues that could come on the on the way um so if you look at the generic ipcc reports you see those kinds of nice uh simulations of of global transition
Pathways uh where uh either you have the Baseline as uh the business as usual trajectory or different scenarios uh reaching more or less 1.5 degrees or or two degrees uh but this is also this is this very uh aggregated View um uh and and that and the the problematic of crossborder uh impacts of such shift a brutal shift in a way uh in a very short time frame are not really uh really addressed so uh we we basically raise uh five um essential points that uh let's say should be embedded in any analysis of climate
or mitigation strategies either from a country single country perspective or from a a regional or Global Perspective one of those Trends is the relation between geoeconomic fragmentation and uh the transition and you've probably seen some of literature some literature emerging around this this topic of geoeconomic uh fragmentation of course this is the um we we we hear every day about uh about that but there is a more substantial link between uh transition the the the low carbon transition and GE and geonic fragmentation that which means that if you don't take into account the current factors
of geonic fragmentation to think about uh mitigation strategies you miss an a very important point but also if you don't consider how M uh a decarbonization strategy might generate a specific geoeconomic fragmentation by itself you also missing an important Point um the second point which is let's say maybe more positive in a way is the rise very rapid rise in renewable dominance um the the the costs of of most renewable sectors is reaching uh threshold tipping points uh in many regions of the world where basically uh it becomes competitive in comparison with fossil um fossil
sectors that's not the case every everywhere and this is also perceived sometimes as a risk or geopolitical Risk by by some regions in the world that would like to protect themselves against the dominance of certain countries uh in the in the rise of these renewable sectors third point is the emergence of uh industrial policy as a key economic policy tool and this has started of course with China which has been doing this for a long time already but then followed by uh uh the US with the IRA law so it not saying that this is
exactly the same approach but it it belongs broadly to the uh the notion of industrial policy and Then followed after that by uh uh the European Union with this their green uh deal green deal industrial industrial plan Net Zero industry act and an specific act on critical minerals um so different approaches to Industrial policies which so far um leave the the rest of the world a little bit alone uh with no uh fiscal capacity or Finance Financial capacity to really follow this move by the the big uh these big three uh regions so that's the
a key point also that could feed back into the geoeconomic fragmentation because you could see uh big emerging countries uh facing uh difficulties to uh follow the industrial policies of the uh China or the Western world uh and then saying okay then uh the transition is not for us um then there is the question of uh a high high inflation regime in the transition so we've we've been experiencing a phase of high inflation that was Supply driven this is now coming down slowly but you can think that the the the transition itself or an accelity
transition will create uh similar kinds of Supply driven uh inflation mechanisms because of bottlenecks in the restructuration of the uh Supply chains uh to be able to reduce uh Emissions on time so this is another factor that uh belongs to this uh what we call this mid transition period and finally the ecological crisis of course is exacerbating the previous factors and make make them more uh difficult so let me just look very briefly into each one of those here I just I don't want to elaborate more on on geonic fragmentation I I'll show an illustration
later on in the case of critical minerals uh this comes from another IMF paper that was the first uh at least in in those multilateral institutions uh to to start fully uh um confronting with this uh this problematic of uh of geoeconomic fragmentation from the perspective of an institution that's supposed to defend a global multilateral order um on the the the question of the rise of renewable dominance uh usual graph that maybe you you've you've all seen is this one comes from the the ipcc and you have different uh studies looking at different regions uh
in the world uh but they show basically that uh the cost of photo voltic onshore wind offshore wind solar power and even batteries for electric vehicles uh is going down at the same time as adoption is uh is um is increasing uh uh at an exponential scale so there is a bit of a of a joint dynamic between more diffusion faster diffusion of those Technologies uh so more adoption and the reduction of cost uh up to the point where it becomes um On a par with alternative or with existing fossil uh Technologies so tipping points
have been crossed uh in China in Europe more slowly in in the US on on on F on solar photov volti it seems that the tiing point is global so there are different uh RMS of adoption and diffusion of those Technologies but this is the more um let's say positive trend now there are reactions as I was saying before uh depending on where the your country or where where the region is in the Glo in the global supply chain of those uh Technologies and that's a feedback loop in a way to the uh geoeconomic fragmentation
uh Point uh very quickly uh the emergence of um of industrial policy as uh a new policy tool for uh climate U policy I mean until very recently and even now most uh let's say multilateral institutions uh are advocating for carbon prices carbon markets Etc so certainly from the World Bank side this is still also the main uh the main message but uh these messages are facing a new reality which is that no uh of course carbon prices are covering more and more regions of the world uh either taxes or or or markets but uh
the pric are are relatively low except in Europe and uh there is no clear sign that this is what's uh really uh making the new sectors uh uh emerge for the transition so that's and the the clear message is that it's it's actually something else that that makes those new sectors emerge um so you have different reactions to that um the EU has come last in this in the sphere of industrial policy and it's just really starting to uh to see what what it means uh because it has it had from its Origins a very
much Market approach to uh to climate policy this very now well uh built uh EU ETS system and very much willing to protect now this EU system with a carbon border adjustment mechanism um so this is in a way a non-cooperative move as well so you can say that it's good because it creates uh more a faster adoption of those Technologies and a reduction of costs this industrial policies but at the same time because it also um creates the new Supply chains in specific regions it excludes others from um from the new uh new uh
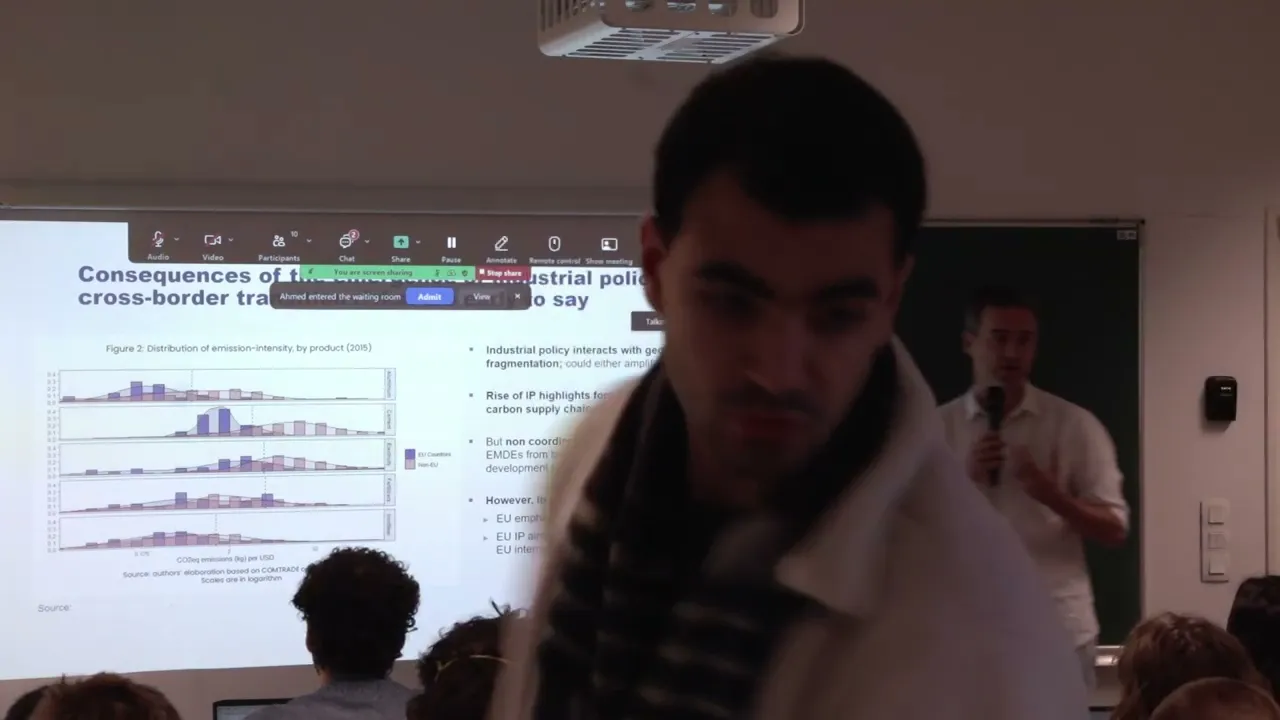
uh let's say green growth sources if you want um so if you look at the effect of the carbon border adjustment mechanism of the the EU uh and uh on the five sectors that that are covered by the by the cbam you can see that four countries uh that have relatively similar emission intensity for that specific technology so here you have on the x-axis you have the emission intensity uh for aluminium cement electricity fertilizers and Iron and Steel and what's in uh in blue is the EU countries so you have the the average the the
the distribution of of of emission intensity uh uh by EU countries and the distribution of emission intensity for the same technology for nonu countries so uh in this sector for example Iron and Steel you see that the distribution is quite similar so you could argue that cbam will uh basically uh have not not much of an effect on um uh on the the trade relation between uh between the EU and the non-u countries uh for uh uh for that specific sector except that maybe there will be an incentive for everyone to improve uh the the
the emission intensity but for those with very different distribution of emission intensity then the effect could be very different in a way where the non-eu countries would really look for new partners alternative Partners than uh the European Union and redefine in a way uh trade routes uh if they can or uh or or or face very difficult uh uh times uh export in the same uh the same product so you have depending on the the structural characteristics uh of the Technologies technology by technology you can have very different uh crossborder effects of uh policies such
as the carbon border adjustment mechanism okay I'll I'll be very quick on on that one because uh I think that was of course more of an issue when we when we were in the middle of the the in the high inflation phase but I think that's the argument still very much holds in the sense that a high high speed decarbonization which is all we want uh will probably generate uh uh High inflation uh uh moments or periods because of from the supply side and so you know way we' we've we've uh created a memory of
how to react to supply side inflation uh at least there was debate around that with ideas like control of prices for essential uh um Goods uh or more strategic uh um well strategic price controls yes and so this this is a useful debate in a way that we can apply uh in the near future if and when there is a a a more ambitious uh transition uh that that that's put in place okay the last last one is kind of obvious we were two days ago in the middle of like two hurricanes one one one
on the European Shore and the other one in the in Florida um and that actually has an effect also on the transition Dynamics itself so we can't consider separately mitigation and let's say adaptation or or climate impacts and you see here for different types of um uh energy sources and the ren the re renewable ones how they are uh how sensitive they are to temperature increase precipitation sea level rise uh high high speed winds and and and wildfires and so your the transition May is becoming only more difficult uh when a climate impacts are exacerbated
okay so that LEDs us to that led us to Define this notion of mid transition period so as I said in the ipcc you see this very uh um smooth uh scenarios uh which tell you uh okay we're we we emit so much now we need to move to Net Zero that's uh the different path how you how you could make make it but without acknowledging the the difficulties that you face here right and that's uh and and what we think propose in this paper is to think about this period very specifically and uh and
suggest that to to Really list all the feedback loops that could backfire on your intentions to do the transition or to accelerate the transition and consider uh a whole spectrum of policies that would need to be mobilized to go through that uh very difficult period when you have basically two systems that coexist and that contradict each other and at the same time some of the climate impacts that uh that uh starts uh unfolding uh so now what I wanted to uh say I wanted to move to uh two let's say examples or two uh Focus
okay one is taking a bit of a broader um um approach so taking not just the climate issue but the planetary boundaries framework and look at uh how much countries are uh contributing to uh or how much the trade between countries so this crossborder Dimension again is contributing to uh planetary boundaries so I guess you all know more or less about planetary boundaries so I don't have to uh to repeat all this but that six of the nine boundaries transgress I think there is 7 one 7th that's almost there um and what's interesting let's say
here is that by taking a country level approach and looking at the the trade between countries uh you can better appreciate how uh countries are positioned in their contribution uh to uh the different dimensions of the planetary boundaries and actually of course you would expect some kind of North s uh um Dimension to it or uh opposition if you want but you have a picture that is a bit more complex than that even if that's a clear Trend but that that's also there is a there's more more to that let's say um so that's the
goal of the draft paper that that was shared I think to to all of you which is to understand the pressures exited by global trade uh over the planetary boundaries um and find which countries and economic activities uh lead the pressure over each one of those planetary boundaries so by the way this this work has been done with two colleagues G magach who was with us half an hour ago U and Gabrielle Caro who is a former student from Epoch I think so you may know him um and so uh previous research on on on
on planetary boundaries is uh usually at has been done usually at the global level so you have these regular reports on where we are in the in the landscape of planetary boundaries and and now more and more you have these country exercises as well so for example in exercise on Chile looking at how Chile contributes to planetary boundaries there's some some on France actually that was done by Adam um and and uh and and some uh um science s and this is this appears more and more but there's not so much on the how the
relation between countries uh is um uh contributes to these planetary boundaries so we basically use uh uh a meth a method that's U where we measure the pressure on uh of trade on planet on the different dimensions of planetary boundaries using a a multi- regional input output database Gloria which and we were lucky about that has almost all the proxies we we can find for all the dimensions of panary boundaries so we use it just for the year 2021 um which maybe is uh uh kind of bias in a way but you can consider also
that mrio are uh very much uh giving the structural aspects of uh the structural aspects of the the the the demand in across countries so that doesn't change so fast right so it could should give a good indication of um this country sector um uh impact on planetary boundaries um Let me show first this uh how we measure planetary boundaries in the paper so this is how it is measured across the the dimensions that's that are already crossed uh in the original papers so the the proxies that are used by the the team around rockstrom
and the peak Peak B Stam and this is how it is Pro proed in our paper so it's a reduced form a reduced form version of of planetary bound but it's still quite uh quite good in the sense that it can cover most uh most aspects oops so first uh first way to look at the results is to understand uh how much trade contributes at an aggregate level across the different uh planetary boundaries so you have here in yellow the not traded part of the planetary bound of the planetary boundaries pressure so you you see
that the trade only represents on average around 20% here more for the novel entities around 50% um but why so why do Focus so much on trade right because trade uh create uh determines not only the relation between countries but usually uh trade itself has a structural impact on how countries produce themselves within the country so it's it's it's much more than just trade uh trade in Goods that explain that that is explained uh by trade so now we focus on those 20% and we look at the uh share of planetary boundaries pressure exerted by
different income groups so you have low-income countries orange medium income countries uh kind of blue and high income countries in in a green and you have the different planetary boundaries here so not too much of a surprise here at least for the first ones where High income countries and medium income countries represents the the bulk of the um of the the pressure uh on planetary boundaries but a bit of a different picture here with water stress climate change and novel entities where we we see high income countries really uh uh moving up in terms of
the responsibility uh on planetary boundaries through uh trade another another way nice way to see it is to look at the planet planetary boundaries pressures between different regions of the world and we take here just the biochemical flows uh planetary boundary and okay this is be this beautiful colors but what it shows is basically that you have the Latin American region which uh has the uh biggest uh export footprint on planetary boundaries if you look at exports but where does it export it export to to uh uh East Asia and the Pacific region M Metal
income so China is there um and then you have the EA region right so e Europe uh Central Asia and so you have a different story here that's that that comes from the import side right you see that um the the region which has the most uh uh impact on planetary boundaries from an import point of view is the East Asia Pacific region and then the Europe and Central Asia and so we have those graphs for all of the planetary boundaries and with quite different stories depending on the type of planetary boundary that you consider
which is not so much of a surprise because behind each one of those planetary boundary you have actually different sectors that contribute to uh those planetary boundaries so and each region of the world has more or less uh uh specialities in those uh in those sectors okay last way I think to to look at it and is um to look at to bring together this Import and Export story so let's for example I don't know take a look at this one so you have East Asia Pacific High income and you have all the planetary boundaries
there and in blue you have the import story in yellow the export story so you see that East Asian Pacific uh Imports has a has a has an import side footprint on planetary boundaries on the biodiversity and L land use aess and an export food uh footprint on planetary boundaries like quite well distributed across the different uh planetary boundaries so this is a way to qualify um a bit more geographically um this crossborder let's say exchange of plantary uh uh boundaries Footprints so this is still we using this kind of framework of uh um looking
focusing on the crossb effects of um of the environmental transition or the the change in the global environment and we're qualifying across different regions and across the the uh different planetary boundaries let me move I don't know how much time I still have good I think I should finish on time so let me move to the second example so again we are focusing on this crossborder Dimension which we think is crucial to understand the Dynamics of this mid-transition period and we look into uh the question of critical minerals in the transition so just to uh
give you a a bit of a General framework you can consider that the the the transition so we back to the climate aspect again the trans the transition will generate uh changes uh AB changes between these different categories of countries uh if you simplify a lot you have fossil exporters you have importers of green technologies you have exporters of critical minerals uh you have exporters of uh uh green technologies and fossil importers okay no country is purely one of those thing maybe except Saudi Arabia for the fossil export country or yeah but all of them
are a bit of mix of that but if you want to simplify and and and and understand uh the issues you can you can look at that graph then what we're doing here is take the G20 countries and try to place them in that in that space right uh so we have here on the x-axis uh kind of indicator of of uh uh dependence on fossil uh fossil exports that's the xaxis the y-axis is uh a measure of net exports of of critical minerals and then the color of the points the color of the dots
um shows how uh close the country is to develop new the new uh emerging new green sectors so it's an indicator of uh green uh it's a green complexity index that you may know already about right so of course if you're red you don't have a a very high green complexity index if you're green you have high green complexity index so when you consider in with these three dimensions we we can measure more or less the those those five archetypes of countries uh so you see Saudi Arabia here really far on the on the on
the index of fossil dependency Russia bit metal of the road here and South Africa quite high on the next net exports of critical minerals and then group of countries here which are like more neutral on those two Dimensions but have different um uh levels of of U technical capabilities in terms of the new emerging sectors so one question uh here is how the in in specifically the critical mineral Dimension will change um the relations between countries or could change uh the relations between countries um so sorry I'm switching to French French I didn't have the
the time to uh to re uh to rewrite the slides uh in in in English uh quickly but uh let me I'll do it uh in English Engish myself so uh I don't I don't think you NE necessarily need um a good introduction to critical minerals and their role in the in the transition right so I will I will switch to the key key graphs that you can uh uh grasp so first this um this graph shows the extraction of mineral resources uh from the' 70s to uh almost today and compare that with a global
GDP so it just says that um we have never uh experienced such a high level of uh resource extraction and this doesn't doesn't seem to change much with the uh uh with the transition on the quite on the contrary uh in effect we need lots of different minerals to build batteries uh here it's cell phones uh to build uh wind turbines um and you have here a kind of summary list for solar wind Hydro bioenergy Etc of the different minerals that are needed uh uh to uh uh to develop those sectors um so uh there
is a recent push relatively recent push to better understand um how that could affect the Dynamics of transition the Geo economic fragmentation as well so we have essentially the International Energy a agency that has starting to shift the uh International critical mineral agency almost uh like issuing many many reports on on the topic the World Bank also has uh um an important report in 2020 uh on the on the issue trying to first see which which are those critical minerals exactly and they are not defined in a um geological terms it's not they're not like
rare earth metals uh they are defined because of the their uh their needs their demand for these new sectors and these new technologies um yeah so uh any scenar scenario uh of uh future transition shows uh skyro skyrocketing needs of uh many of those um uh minerals the simulations are very different from one exercise to another but basically there are some very worrying um Trends compared to the current capacity to uh uh extract uh or even given the result reserves that we can observe on some of those minerals so that that's a 2021 report by
the International Energy agency that shows uh depending on the transition scenario that you you take into account that you will have a two-fold or four-fold increase um of the the need uh of of those critical minerals and and uh and what where where the demand uh will come from uh this one is quite nice actually if you like uh like to see long long history right so you start in 4,000 Before Christmas uh before Christmas before before Christ and uh you uh you end up in 2050 and so that's the the kind of GE geological
period we we will be in in the coming years or we are already and so uh in 22 years alone if we if we uh believe in the projections for the transition uh we will be extracting more than anything that has been mined basically in human uh history uh okay so that that has some effects uh on prices so we're back to the uh inflation uh uh Supply driven inflation feedback loop you can see that uh since the 2019 so a bit of covid related a bit of Ukraine war related but not only that you
have more variability at least in the prices of uh many critical minerals and on average an an an increase you had a very steep increase in 22 that's like um is now a bit lower but not coming back to the uh to the previous levels uh you have some projections that exist from the AMF uh that that tries to look at the potential impact on prices of Net Zero uh policies on copper nickel Cobalt and and lithium and in red you have this Net Zero scenario a Medan of the the different uh transition scenarios taken
in into account um and you see on average also uh an important or noticeable impact on prices um so that's a 2021 uh study now what's uh now I will show I I will focus on these different types of risks that could emerge out of uh um this critical mineral story there is the GE GE geological risk I I want to speak about that I'm not specialist at all but I will look at the different risks on Geo economy and uh and environment so uh this is a a picture that that gives you um the
the share of uh of the three top countries by uh sector so here are the fossil fuels for reference and then critical minerals right um so uh in total production for selected minerals and fossil fuels in 2019 so that's like more for the extraction side and that's for the processing right which is an important factor as well so you see clearly from the just the comparison between that picture and that one or so that one on fossil fuels and that one on critical minerals that the the the geography uh is completely changing right where you
have a us let's say us Saudi Arabia Russia based uh geography uh and then a much more diverse geography for critical minerals with some strong um um let's say strong um representation of China and here in processing it's China overwhelmingly uh uh dominating the the processing sector um if you take the point of view of the European Union there was a paper by decot Al 2024 uh from the London School of Economics where you can find this analysis of the dependency of the European Union to uh Global suppliers of critical minerals uh and you see
of course a strong dependency on China Australia and then a little bit less Russia some uh Latin American countries and and the and the US um so this is a uh a kind of study that all regions of the world are now doing and implementing policies to try to strategize their um how much they would need from which countries Etc uh so it's often said that China has a very strong position which is true um you can um so it it but but actually the the the picture is a bit more complex than that as
we said China is uh dominating the the refining side and only partially dominating a few of the uh of the critical minerals and then it depends on how you measure dominating so that's what we were uh willing to investigate a bit more in that paper which was how do we measure um the ownership of the minds and we have uh basically different ways to measure that the kind of geographic uh way so that simply where in which country is the mine located so that's the left hand side so you have different critical minerals and you
have the the countries that are dominating in terms of purely geographical origin uh the mines so China is there in in in red but it's like not really everywhere it's you have Australia you have Brazil uh you have South Africa and and and and others now you can also look at um who owns the mine and where is that owner located so that's the second measure of ownership um so here you may have a little bit more of China but you also have a very strong uh South Africa you have quite strong Australia as well
so it's a different uh geography that uh that you can uh you can see and then last point is who owns the owner who has has the uh the shares the the financial control over the owner of the m and here you can see the US completely dominating this uh in in purely Financial ownership terms uh only in the lanides you have China like dominating the uh the picture so depending on the measure that you you're taking you have a very different uh view of potential GE geoeconomic risk or Geon fragmentation so let me finish
with um a c I think that's the last really interesting graph we we we what we're trying to do there there is to look at potential scenarios of geoeconomic fragmentation so how do how do you measure Geon fragmentation that's difficult uh there are many ways to do it we chose one which is how countries vote uh in the in the UN General Assembly and how uh far countries are one by one one against one if you want um on the votes in the uh UN General Assembly so that defines um a geopolitical distance that's on
on the x axis here right so uh the father you are uh from uh on the right hand side the the the most geopolitical distance you have between countries owning that kind of critical mineral right so let let's take Vanadium for example if you take the um geographical ownership measure uh geographical concentration measure uh of of vanadium or if you take uh the legal origin uh measure uh uh of concentration on the vum sector or if you take the geographical uh measure of vanadium so you end up with quite different geopolitical uh implications right when
you have the when you have the three uh points which are at the same place that means that um the three measures of concentration are quite homogeneous in terms of the geopol GE economic fragmentations uh uh measure scenario that you have once they are when when they are split it means that actually you could have very different uh stories uh coming out of a geoeconomic fragmentation depending on which ownership definition you uh consider right so that's just what the the graph says um and yeah I will I will stop here I think uh just saying
that I mean this is really an important topic emerging more and more and just this graph uh proves it you have the number of policies targeting critical minerals by country and it starts in 20 2016 so we are here in 2024 so there like it's it's almost an exponential growth in policies focusing on critical minerals and so there is Need for more more studies on on uh what what the impact could be and also what kind of policies could meet mitigate those effects in the transition process thank you very much [Applause]