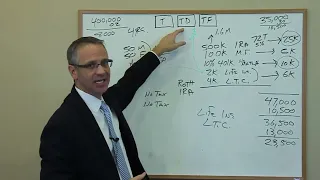
consumer advocate tax expert and educator ed slot is here to help you rescue your retirement by following his time-tested method of avoiding the five silent retirement killers The Wall Street Journal called best-selling author Edie slot the best source of IRA advice and USA Today said it would be tough to find anyone who knows more about IRAs than CPA slot here's n slot hi everyone I'm ed slot and this program is called life insurance for a life and beyond well first why am I talking about life insurance because life insurance may be the most underused strategy
to protect large retirement balances from being decimated at the highest levels of Taxation so who's most at risk those of you who have the largest IRAs or other tax deferred savings accounts if you have taken the time to watch this DVD then I know you want to learn more so before we begin just so you know I don't sell life insurance so why should I care I don't sell stocks bonds funds insurance or annuities I'm a tax advisor but it's all about the taxes I also believe most people don't understand how life insurance works as
an effective planning tool I don't sell it and I'm no expert in exactly how all the various life insurance contracts work that's why there are life insurance professionals that you need to work with to fill in all the details but I do know the end result it's like a car I know it gets you there but I don't know how the engine works but I do know how life insurance can fix lots of money and retirement problems and even create wealth and tax-free wealth and you know I love tax-free I only care about the end
result the benefits the benefits to you I want you to know how powerful the end result is I want to give you enough here so that you'll Stan what life insurance tax planning can do for you and your family both during your lifetime and after your death so why don't most people take advantage of life insurance because every time you hear life insurance some people just tune out whether you put it off and most times you hear about life insurance you're hearing about it from someone who sells it so maybe you feel like you're being
sold rather than being advised maybe you think they're just trying to sell me something so you think I'll avoid the meeting or avoid the discussion and maybe you're right maybe you feel that you're just being sold so you don't see a benefit to you but I'm here to tell you you could be wrong I want you to understand what's in it for you from an unbiased objective tax benefit point of view well now you're meeting with me so let me tell you why I believe life insurance is the missing piece in most people's retirement and
estate plans the tax exemption for life insurance is the single biggest benefit in the tax code I don't even think life insurance professionals use it enough or appreciate it enough maybe that's why they don't sell enough of this product I put this brief guide together for you in the hope that you'll view it and see how tax planning with life insurance provides powerful benefits and then you'll continue this conversation with your life insurance agent who can fill in all the details except that now when you meet with him or her you'll have a better understanding
of the benefits and what questions to ask you'll definitely be more involved in the discussion especially when it comes to your retirement first let's see what the problem is and let's see what the solutions are the good news is that taxes are generally money problems and life insurance puts lots of free money tax free money in your pocket so most tax problems can easily be avoided with great planning here are both the problems and the solutions and I want to give you this program on two levels the problems that can affect you during your lifetime
and the problems that can affect your beneficiaries your family after your death so why would you care about a solution if you didn't think you had a problem well if you have taxable savings you have a problem and so do your beneficiaries in my public television program I tell you about what I call the five silent retirement killers and they must each be addressed and one of them is risk most people think of this as investment risk as in the stock market but when it comes to your retirement savings especially taxable IRAs and 401ks and
even bigger risk is tax risk many people think that simply having retirement savings is enough it's not it's what you keep that counts after taxes there's a mortgage on your tax deferred retirement savings most of that is owed right back to the government in fact future taxes could be fifty or sixty percent or more by the time you reach in for yours that's not real money the only real money is tax free money spendable money where you keep it all plus with IRAs and 401ks you have to take required minimum distributions on that money after
you reach age 70 and a half years old and you're forced to pay taxes on the government schedule not yours that's the government plan that's not real money since it's all subject to tax are you wondering what future taxes could do to your retirement security you should be you know why you've caused the problem especially if you've done everything right you saved you sacrifice and built a healthy retirement account at 401 K or an IRA so what's the problem with IRAs the problem is their tax deferred not tax-free that money will be taxed at some
future point with an IRA a SEP IRA a simple IRA 401 K 403 b or any other type of tax deferred retirement plan you received your tax deduction upfront your retirement funds have grown tax deferred all these years so far so good you've done well but there'll be a day of reckoning you'll owe income tax when you begin to withdraw just when you need the money the most how much tax we don't know that's the problem you won't know that until you need the money the most in retirement or after you die when your family
inherits this uncertainty keeps people up at night so that is the tax risk but there's another risk market risk your retirement savings and other investments if invested in the stock market are also at risk of being lost to more Wall Street fraud or manipulation or a market crash at the wrong time for you so let's review up to this point typical tax deferred retirement savings like IRAs and 401ks are subject to two major risks investment risk and tax risk now here's where the life insurance comes in life insurance can be used to remove both of
these risks investment risk with life insurance you get certainty a guarantee you cannot get a guarantee in the stock market and tax risk you eliminate that by never having to pay tax on this money so you need to create a plan to move your money from accounts that are forever taxed to accounts that are never taxed life insurance is the best provision in the tax code to do that wouldn't you sleep better at night if you knew your retirement savings were no longer subject to these risks but still the benefits are misunderstood and not used
enough in planning so what are the benefits and exactly how would you use life insurance in your planning first when I talk about life insurance I'm referring to permanent insurance permanent life insurance even with permanent insurance there are several options so you need to speak with an insurance professional for all of those details and I mean permanent insurance as opposed to term insurance which is more for younger families looking for the maximum death benefit so here I'm talking about permanent insurance for those looking for retirement security and a state protection as I've already told you
you have a tax problem especially if you have significant funds in taxable and tax deferred accounts your family will also have a problem after you die if no planning is done and they inherit mostly taxable funds they're gonna be dealing with these tax issues too they also may be dealing with the state taxes depending on the tax law when you die and that changes all the time so you need to plan for the worst case scenario and hope for the best your family will most likely also have a liquidity problem if retirement funds and other
assets have to be cashed in quickly in order to raise money after death for taxes and other post-death expenses money is often needed after death to resolve all kinds of issues besides taxes I'm talking about family squabbles etc family members wanting money more quickly the last thing you want is for your family to have a fire sale especially if there's a family business or other valuable property in your estate you don't want your family wasting or cashing out retirement accounts or other valuable property prematurely because cash was needed quickly you need to do a liquidity
test right now so you can see if your family will have a cash problem after death to gauge the problem what I do is I take clients through my own type of liquidity analysis because most people are not liquid enough to avoid having their families starting to have to sell off investments cashing in retirement accounts and triggering unnecessary taxes so what is my liquidity analysis still it shows you how much of your estate can be turned into cash quickly without triggering taxes or losing property value cash is often needed after death even if there are
no estate taxes and remember that's only federal taxes don't forget state estate taxes there are always expenses and the IRA is the last account you would want to have to tap into to pay those bills remember IRAs are subject to both income taxes and estate taxes could be subject to estate taxes which could eat up a lot of cash quickly you can work with your adviser on your CPA or accountant on this to this liquidity analysis to go through it with them but here's what we do we have clients make a list of all the
assets you own so do that now make a list of all the assets you own less liability mortgages loans debts etc in other words your net worth now you have this property code all the property as either liquid or non liquid by liquid I mean assets that can be most easily and quickly turned into cash without triggering attacks what I call money you have to pay a toll on to get it tow money you're left with basically cash here's what I mean I arrays I wouldn't include as liquid assets you might say oh I have
all this money in my IRA but you have to pay a toll to get it it's not liquid you have to trigger taxes to get it so I wouldn't put I or a in with liquid assets or cash so here's what we do we do a percentage a fraction the numerator is liquid assets basically cash your cash your bank accounts and I don't mean actual cash but bank accounts that you could get money easily out of without triggering a tax bill and again do not include IRAs a 401 k s-- here sure they can be
cashed in but there's a toll on that money and that will trigger attacks include only assets that could be sold quickly without triggering attacks or other expenses or losing significant value like a fire sale sure you can get money out of it quickly if you sell for a low price so that's the numerator basically liquid cash and accounts now the denominator is the value of your entire estate everything including the cash including your assets business interest real estate include all property in addition to the IRAs now look at that percentage look at that fraction for
most people cash over the total estate is about 5% of that much do you know what that means turn it around in other words this means most estates are 95% illiquid that's a problem unless you actually do have a ton of cash laying around available but most people don't most people when I do this liquidity analysis at that moment realize that they have a huge liquidity problem so now you know you have tax exposure stock market risk and a liquidity problem so how can life insurance help two ways during your lifetime so there's something in
it for you right now and after your death during your lifetime you have the ability to reduce both stock market risk and tax risk by moving your money from accounts that are forever taxed to accounts that are never taxed you can actually do that two ways Roth IRAs and life insurance both cost money now but with life insurance you'll be creating a bigger pot of tax-free money later when it's most needed it would be great if you could do both and turn your entire estate into a tax-free windfall both during your life and after death
but the more powerful way is with life insurance and again I'm talking about permanent life insurance that has cash value you can contribute more with life insurance than you can generally to a Roth with a Roth IRA though it's easier to access your money if you need it Roth IRAs are income tax free - but they are a part of your estate and subject to estate taxes but Roth IRAs provide no additional death benefit as life insurance does life insurance comes with a guaranteed death benefit and that benefit unlike a Roth IRA can be set
up to be a state tax-free - so what can you do to remove both the stock market risk and the tax risk first you can leverage your retirement savings like an IRA if you have a large IRA it may pay to draw it down now and pay tax on the distributions then use those distributions to invest in a permanent life insurance policies remember that tax rates are still at an all-time low right now so now would be the best time to strike even if it costs you some tax money it still pays because you are
lowering your tax exposure on your IRA and anyway after age 70 and a half mandatory withdrawals from the IRA must begin whether you like it or not since the money will eventually have to be withdrawn anyway it may as well be leveraged by using the money to pay the life insurance premiums you're basically paying off the mortgage on your IRA early so you never have to worry about tax risk and the funds invested in your permanent life insurance policy are now growing tax and risk free and you can have lifetime access to the cash value
tax-free if you need it for retirement so during your lifetime you can in effect turn your taxable IRA and other taxable savings into a tax-free savings vehicle it's really just like changing pockets from taxable accounts to tax-free accounts except that now you've also built in a guaranteed death benefit to benefit your family it's generally judgment-proof to the life insurance I'm talking about if you have other taxable funds you might want to keep those protected from future taxes too many people who are looking for places to shelter money from taxes stock market risk and lawsuits are
stuffing taxable money into permanent life insurance as a lifetime personal protected savings account all the growth is tax-free for life and beyond so those are the benefits to you during your lifetime what about post death benefits for your family well if you don't need to tap into the funds during your lifetime your beneficiaries are guaranteed a death benefit the stock market has no such guarantee your family will now have guaranteed access to a ton of tax-free cash tax-free means they keep every cent no tax erosion here they will have tax-free cash to pay estate taxes
if needed to pay expenses debts mortgages all without triggering taxes or having to sell a family business or other valuable real estate or other property that could trigger taxes if they had to use your IRA to pay these bills they would first have to pay income taxes and maybe estate taxes too leaving very little to pay bills or for them so don't just sit there and admire your IRA like most people do leverage it now use it leverage it or lose it to possible future higher taxes never underestimate the value of leveraging IRA money by
using it to pay life insurance premiums the larger the estate the higher the estate tax having enough insurance money available to cover the estimated estate tax will avoid having to invade the IRA to pay the tax now some people might say but the current estate exemption now is so much higher so there probably won't be any estate tax you know what this has been changing on and off over the years this is not an option you can plan with the estate tax exemption has been changing up and down and you cannot take that kind of
risk anyway what's the downside if there's no estate tax your beneficiaries will simply inherit more money and it'll all be tax-free that's the downside but okay let's continue with that scenario let's say there is no estate tax there are still plenty of uses for life insurance even if there is no estate tax you could use life insurance to replace stock market losses I had a doctor client a few years ago that had this account he had about three million bucks in a brokerage account and he said to me I want that to go to my
family I don't want to touch that three million to go to my kids but then the stock market crash hit and he lost a million dollars in the market so now his value is only two million what did he do he went out immediately got a million dollars of life insurance he replaced all that loss value immediately now he still has the three million to leave his kids two million what's left in the portfolio plus a million of life insurance he replaced losses immediately life insurance can also be used to provide tax-free money for your
beneficiaries so they don't have to withdraw amounts in excess of their required minimum distributions here's what I mean you might want to set up a stretch IRA for them where they take only the minimum amounts each year but what if they need more what if they have to take more you don't want them hitting the IRA and taking out more taxable income and especially if it's a Roth IRA breaking into tax-free money so the life insurance can provide them extra money in addition to the minimum withdrawals so they can stick with the minimum withdrawal schedule
and any other money they need they use the tax-free life insurance money this will keep their income taxes lower since the excess IRA distributions would have been taxable the money they use from life insurance is tax-free also this allows them to stick with a stretch IRA schedule instead of the leading the IRA balance before its time and it's even more powerful for a Roth IRA this can also allow inherited Roth IRAs to last longer and continue to grow tax-free for your beneficiaries life insurance can also be used to simply create wealth your family can easily
end up with millions more than you ever had all tax-free that's why I talked to clients I give them this scenario first like I said before we find their net worth the entire value of your estate and then I ask if I could create a plan so that after you die your family will end up with your entire net worth whatever that is or much more would that be a good plan of course I'd be a good plan where do I sign up for that who wouldn't want that does that mean there were no taxes
or other expenses that depleted the estate no but we plan for that and those items can be paid from the additional tax-free life insurance money with plenty more left for your family that's how any family's assets can be leveraged with life insurance to eliminate the effect of taxes and turn what was a taxable estate into a much larger tax-free estate here are some other uses for life insurance planning if you have no retirement you can actually create one with life insurance and have death benefit protection to all guaranteed by moving other taxable money into your
permanent life insurance policy this provides a lifetime benefit for you life insurance can be a pension alternative to providing beneficiaries with a tax-free stream of cash for the rest of their lives similar to the stretch IRA except that the life insurance is better than a stretch IRA because it's tax-free and another benefit money solves a lot of problems not even always money problems families that don't get along and it's not usually your children it's the ones they marry we had a case where one of the daughters just wouldn't even talk to the other three kids
so mom came to see me and she decided to take out five hundred thousand dollars of life insurance naming the four children is equal beneficiaries when mom died it didn't matter one of the daughters wasn't talking to the others life insurance does not pass through a will it is not subject to probate or income tax so each of the children got their hundred and twenty five thousand dollar checks with no fights and no contact it said but it avoided a ton of legal problems will contests and other expensive and nasty arguments they just got the
money straight out so this is the basic strategy turning taxable money into tax-free money using the tax exemption for life insurance moving your money from accounts that are forever taxed to accounts that are never taxed as tax rates increase tax-free becomes much more valuable life insurance like Roth IRAs removes the uncertainty of what future tax hikes could do to your retirement savings but is it all good what's the downside nothing's all good what's the downside you might not qualify maybe a to Ill well that's something you might want to look into annuities for that that
also gives you a guaranteed stream of income for life another downside well obviously you have to commit to funding the policy if you don't put the money in you won't have it you also need to have funds available to invest but that's where your IRA and other taxable funds come in but if you don't have it maybe it's not for you life insurance may not be for everyone you don't want to go broke with it if you don't have enough assets you probably don't have a tax problem and then it might not pay for you
maybe you only need enough life insurance to protect your young family in case of an early death that you should always have the bottom line is that life insurance provides tax-free cash tax-free is always the best source of money and it also solves lots of non tax problems well this is all good but people make mistakes when it comes to life insurance planning and understanding life insurance here are the five most common life insurance mistakes mistake number one thinking that life insurance is a cost and not looking at it as an investment if you put
money in a bank account that's an investment this is the way you should look at life insurance you want to put it in as an investment and the bigger the number the more you'll have it's not a cost it's your money it's an invest men item number two trying to pay the lowest amount for life insurance it sounds good right do you want to pay a thousand dollars or ten thousand dollars for the policy with permanent life insurance you might want to pay more like I said in item one think of it like a bank
account you may want to maximize the amount you have available so you may want to put more in mistake number three not understanding the benefits now I went through some of the benefits before but let's review them for example with life insurance you have a tax-free payout after death and generally it's judgment proof also with life insurance you have lifetime access to cash value tax-free so it won't increase your income it won't cause Social Security to be taxed and you won't lose tax benefits because your income increase like losing exemptions deductions and credits life insurance
is exempt from a state tax if it's set up right and with life insurance you get a guarantee removing stock market risk the government has restrictions on how much you can invest but you generally want to put in the maximum you can mistake number for improper ownership don't own it in your own name why on earth would you want to own something like life insurance that you can't possibly collect on why would you keep it out of your estate we see this all the time with clients it's one of the biggest mistakes made in fact
we had a young client a young couple come in recently very successful couple made a lot of money and we were going through the assets they had and the the husband actually did have five million of insurance and then when I looked at it it was owned in his own name and I said what'd you do that for do you realize that if you died that five million comes right back in your estate and could and if your estate is subject to estate taxes the government could get half of that why would you own it
in your own name you want to keep it out of your estate and I told them go back to your insurance agent can get you know fix this and it's not that easy to fix but it can be fixed there are waiting periods but go back to your insurance professional well when I said that he said I don't even remember who sold this to me so there's just an aside don't you think you should have a better relationship with your adviser you shouldn't own it in your own name it should be owned by somebody else
or a trust the life insurance premium should be paid by the beneficiaries or by the trustee of an irrevocable life insurance trust so that the life insurance proceeds will be a state 2x3 oh and one item here there one downside be aware that if you that if you don't own the policy which is what I'm saying to do not to own it in your own name if you don't own the policy you may only have limited access to the cash value because you don't own it mistake number five not knowing it's tax free I don't
even know if this is a mistake or a misconception can you believe it still people don't know that life insurance is tax-free I get calls every now and then from a beneficiary we did planning for their family and they'll call me up and say Edie I just got this check what do I do with it how much do I owe in taxes I said I told you a million times it's tax free the benefit is so good even when people get to check they don't believe it the life insurance is tax-free so let's review risk
is a silent retirement killer life insurance can eliminate both stock market risk and tax risk and it can be used during your life to create a tax-free retirement fund life insurance is not only income tax free but can be a state tax free too you can contribute almost unlimited sums to a permanent life insurance policy and have tax-free access to your cash value during your life without increasing your income and don't forget about the most basic life insurance benefit aside from all the estate and retirement tax planning advantages life insurance protects families when there's an
early death young families it's hard enough to deal with the loss of a parent but at least life insurance can provide the needed cash so that life can go on without having to make any severe changes due to lost income money for the family tax-free money I never met anyone who didn't wish they had more life insurance especially a widow I like to say that life insurance takes care of families without first going through the government you need to review all of these points with your life insurance professional who can fill in the details but
now you're much better informed and ready for the conversation you might actually even enjoy the conversation now with your life insurance agent can you believe it life insurance is not only the single biggest benefit in the tax code but it's also the most cost effective way to protect a large IRA you need to have a discussion with a competent educated adviser that in addition to being a life insurance professional has the specialized knowledge in retirement tax planning the coordination is essential especially if you've built up significant balances in your taxable IRAs or 401ks most advisors
do not have this level of training so be careful as tax rates increase life insurance becomes more valuable than ever before and there are increases on the horizon you have new to health care taxes coming in as well as higher tax rates you can plan for that now and if it doesn't happen what's the downside you and your family have sheltered that much more money since it won't have to be used to pay taxes here are some of the frequent questions I get about life insurance edie if the tax exemption for life insurance is so
good won't the government take it away no why it's a social reason why do you think our government encourages us to give money to charity because if you give money to charity you get a tax deduction why is the tax code loaded with incentives to encourage us to give money to charity why does the government want us to give so much money to charities because they're broke so they don't have to do it to remove the burden from them it's the same thing with life insurance our government is broke our government wants us to take
care of our families so they don't have to they want us to take care of our families with our own money partnered with private insurance company money so that the government doesn't have to next question I get II D what if I don't qualify for life insurance I have to tell you if more people do qualify than you think I've seen it even with very ill clients so don't assume you won't qualify I leave this to your life insurance professional to check for you more people qualify than you think here's another question I love edy
how can life insurance companies do this they'll lose a fortune oh now you're worried about life insurance companies don't worry about them they have actuaries we're not gonna hold any benefits right away for life insurance companies they're doing fine the answer is it's in the numbers this the risk is spread over a large pool of people don't worry about them insurance companies are some of the most solid financial institutions next question I get II D why doesn't everyone do this you know what I don't know I also think that insurance is not sold properly so
you look at it as a cost or out of that investment many people think they're buying something and they don't see how it fits into a plan like I've been telling you about a good financial advisor or insurance professional can explain the planning aspects edie which is better saving in an IRA or an insurance policy that's interesting life insurance wins hands down let's compare let's compare life insurance to a tax deferred retirement plan like an IRA or a 401k if you compare life insurance to tax deferred plans life insurance has several advantages first with life
insurance you have lifetime access to cash value tax-free and penalty free with an IRA withdrawals can be heavily taxed and penalties - also with an IRA after you're 70 and a half you're forced to withdraw and pay taxes whether you like it or not life insurance provides a tax-free death benefit income tax free estate tax free - ofone properly and with life insurance has no risk of future tax rates increasing I mean they could increase you just don't care just so you know the Roth IRA also provides this benefit the reason you don't care is
because what would you care about taxes if it's all tax-free but here's what you don't get with life insurance that you do get with an IRA and a 401 K with life insurance you don't get a tax deduction like you get with an IRA or 401 but a tax deduction these days is a trap because you'll pay much more in taxes later all right the last question I always get come on in are you working for the life insurance companies this is too good to be true no I told you that before I'm here for
you telling you how to create and build tax-free wealth using the single biggest benefit in the tax code I always say life insurance is the only legal way to print money so there you have it the problems the benefits both to you during your lifetime and for your family after your death a bottom line don't just sit there and admire your IRA or 401k if you have a large IRA you have a tax problem it's tax deferred a sitting duck just waiting to be taxed use it leverage it or lose it to future taxes do
something now while the best option still exists move your money from accounts that are forever taxed to accounts that are never taxed and good luck thank you very much [Applause]