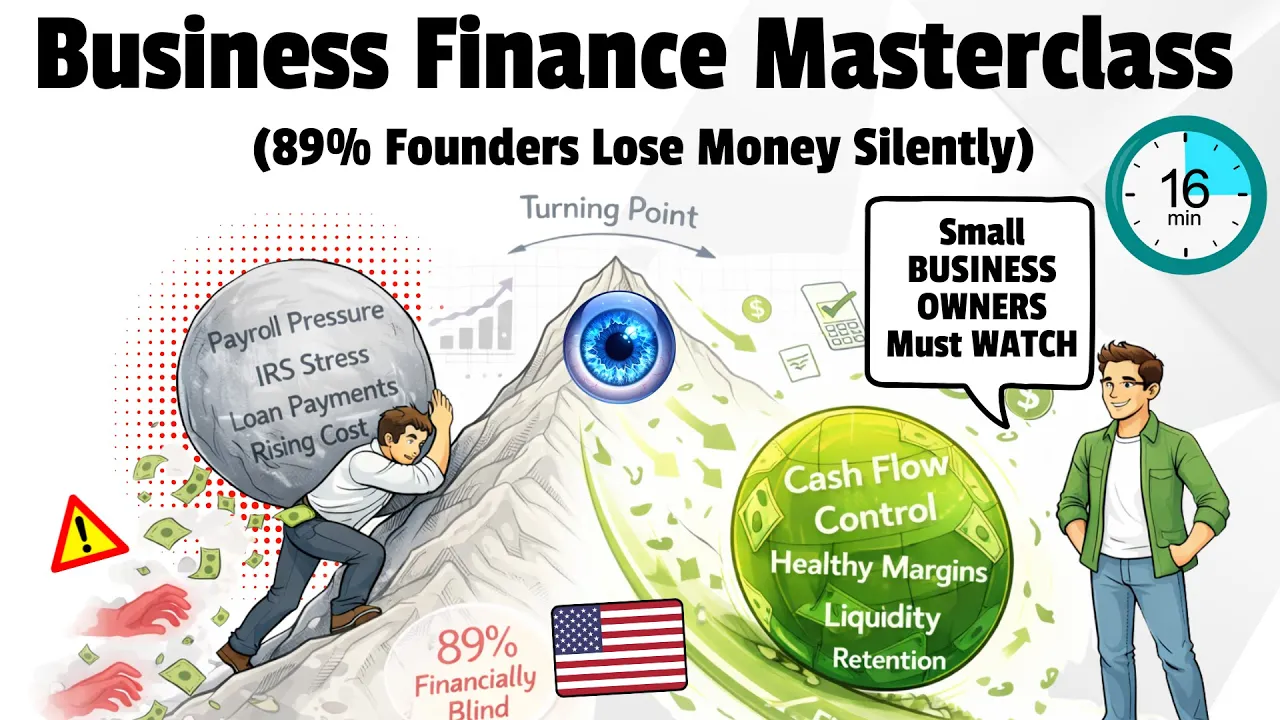
Most US small business owners feel busy but financially blind. Revenue comes in, expenses go out, but control is missing. Payroll deadlines, IRS pressure, loan payments, slow customers, and rising costs create constant stress.
This business finance masterass brings everything together in one place. Stay with this video till the end because missing one layer breaks the system. Grab a notebook, reduce distractions, and watch this from start to finish.
By the end, business finance will stop feeling confusing and start feeling like a system you actually control. Chapter one, foundations of business, finance, and money thinking. Business finance starts with one simple truth.
Money is a system, not a feeling. Many owners run businesses based on hope, effort, and sales excitement. But finance works only on numbers and discipline.
The first core term you must understand is revenue, which means total money earned from sales before any cost is removed. For example, if a company sells products worth $500,000 in one year, that entire amount is revenue, not profit. Next comes cost of goods sold, often called COGS.
This includes raw material, manufacturing, labor, packaging, and direct production costs. If producing those goods costs $300,000, revenue minus COGS gives gross profit, which in this case is $200,000. Gross profit alone does not mean the business is healthy.
After this, we subtract operating expenses such as rent, salaries, software, subscriptions, insurance, utilities, marketing, and logistics. Suppose operating expenses are $120,000. When we subtract this from gross profit, we get operating profit, also known as EBIT, meaning earnings before interest and taxes.
This number shows how strong the core business operations really are. Now comes an important mindset shift. Profit is not cash.
A business can show operating profit but still struggle to pay bills. This happens because of acrruel accounting where income is recorded when earned not when cash is received. For example, if you sell products worth $50,000 on credit, revenue increases immediately, but cash does not enter the bank until customers pay.
This creates accounts receivable which is money owed to the business. On the other side, accounts payable represents money the business owes suppliers. Managing this timing difference is critical.
Another foundational term is working capital calculated as current assets minus current liabilities. If current assets are $180,000 and current liabilities are $120,000, working capital is $60,000. Positive working capital means the business can handle short-term obligations.
Negative working capital means stress, delays, and dependence on loans. You must also understand fixed costs and variable costs. Fixed costs stay constant like rent or office salaries.
Variable costs change with sales volume like raw material or shipping. Knowing this helps you calculate break even point which is the sales level where total revenue equals total costs. If fixed costs are $100,000 and gross margin is 50% the break even revenue becomes $200,000.
Business finance also includes capital structure, which is the mix of owner equity and debt. Equity means the owner's invested money. Debt means loans that must be repaid with interest.
Too much debt increases financial risk. Too little debt may slow growth. Smart businesses balance both.
Understand financial discipline. This includes budgeting, forecasting, cost control, and performance tracking. Finance is not about accounting reports alone.
It is about using numbers to make decisions before problems appear. Once you master these foundations, every advanced financial concept becomes easier to understand and apply. Chapter 2, profit loss and the real meaning of business performance.
After understanding revenue and costs, the next layer of business finance is knowing how profit is actually measured and why profit numbers can be misleading if read without context. The profit and loss statement, also called the income statement, shows business performance over a period of time. It starts with revenue, subtracts costs, and ends with profit.
But each profit level tells a different story. The first level is gross profit, which shows how efficiently a business produces and sells its products. If revenue is $1 million and cost of goods sold is $600,000, gross profit becomes $400,000.
From this, we calculate gross margin, which is gross profit divided by revenue. In this case, [music] the gross margin is 40%. Higher margins mean more room to cover operating expenses and survive price pressure.
Next comes operating profit, also known as EBIT. This reflects how well the business is managed. Two companies can have the same gross profit but very different operating profits due to spending habits.
If one company spends $300,000 on operations while another spends only $200,000, their financial health will differ sharply even with similar sales. Then we reach net profit, also called net income or bottom line. This is what remains after subtracting interest and taxes.
For example, if operating profit is $200,000, interest expense is $30,000, and taxes are $40,000, net profit becomes $130,000. [music] Many owners celebrate this number, but investors and lenders look deeper. [music] One critical concept is non-cash expenses, especially depreciation and amortization.
Depreciation spreads the cost of assets like machines or vehicles over their useful life. If a machine costs $100,000 and is depreciated over 5 years, the annual depreciation expense is $20,000. This reduces profit but does not reduce cash in the current year.
Understanding this difference explains why profits can fall while cash remains stable. Another important term is EBITD DA meaning earnings before interest, taxes, depreciation and amortization. This shows operational cash generating ability before financing and accounting effects.
If EBIT is $200,000 and depreciation is $20,000, EBIT DA becomes $220,000. Many lenders and investors prefer this metric because it shows operating strength. You must also understand profit quality.
High profit with slow cash collection, heavy discounts or rising inventory is risky. For example, if profit increases by $50,000, but accounts receivable increase by $70,000, real cash health is declining. This is where earnings manipulation risks appear, often unintentionally.
Another concept is operating leverage, which measures how sensitive profit is to sales changes. Businesses with high fixed costs see profits rise fast when sales grow, but crash quickly when sales fall. Low fixed cost businesses grow slower but survive downturns better.
Finally, profit should always be compared using ratios. Net profit margin, operating margin, and return on sales help compare performance across time and competitors. Profit without context creates false confidence.
Profit with analysis creates control, stability, and long-term growth. Chapter 3. Cash flow, liquidity, and why businesses die with profits.
Cash flow is the most misunderstood and most powerful area of business finance. Profit shows performance on paper, but cash flow shows survival. Cash flow tracks the actual movement of money in and out of the business bank account.
A company can report strong profits and still collapse if cash flow is poorly managed. Cash flow is divided into three main categories. The first is operating cash flow, which comes from core business activities.
This includes cash received from customers minus cash paid to suppliers, employees, rent, and utilities. For example, if a business collects $400,000 from customers and pays out $300,000 for operating expenses, operating cash flow is $100,000. This is the healthiest form of cash.
The second category is investing cash flow, which relates to buying or selling long-term assets. Purchasing machinery for $150,000 creates negative investing cash flow. Selling old equipment for $30,000 creates positive investing cash flow.
Strong businesses often show negative investing cash flow because they reinvest for growth. The third category is financing cash flow, which includes loans, repayments, equity investment, and dividends. Taking a loan of $200,000 creates positive financing cash flow.
Repaying $50,000 of principal creates negative financing cash flow. Financing cash flow shows how a business is funded. Now comes a critical concept called free cash flow.
Free cash flow equals operating cash flow minus capital expenditures. If operating cash flow is $100,000 and capital spending is $40,000, free cash flow is $60,000. This is the cash that can be used to repay loans, pay dividends, build reserves, or expand operations.
Investors care deeply about this number. Another key idea is cash conversion cycle which measures how quickly a business turns inventory and receivables into cash. It combines days inventory outstanding, days sales outstanding, and days payable outstanding.
A long cycle means cash is stuck in operations. A short cycle means faster liquidity. Liquidity itself is measured using ratios like the current ratio and quick ratio.
If current assets are $200,000 and current liabilities are $100,000, the current ratio is two. This means the business has double the short-term assets needed to cover obligations. Weak liquidity forces businesses to rely on emergency loans.
You must also understand burn rate, especially for startups. Burn rate shows how fast cash is being consumed. If a company spends $50,000 per month and earns only $30,000, the net burn rate is $20,000.
With cash reserves of $100,000, the runway is 5 months. Another dangerous area is cash leakage. Small recurring expenses, poor inventory planning, delayed collections, and uncontrolled discounts slowly drain cash without obvious warning.
This is why cash forecasting is essential. Cash flow management requires discipline. Weekly cash tracking, monthly cash flow statements, and rolling 12-month forecasts help owners see problems before they become emergencies.
Cash flow does not care about effort, intentions, or profit margins. It only cares about timing, discipline, and control. Chapter 4.
Balance sheet power, assets, liabilities, and financial stability. The balance sheet is often ignored by business owners, but it quietly decides whether a business is strong or fragile. Unlike the profit and loss statement, which shows performance over time, the balance sheet shows financial position at a specific moment.
It answers one key question. What does the business own and what does it owe? Right now, the balance sheet has three main sections: assets, liabilities, and equity.
Assets are resources controlled by the business that provide future value. These include current assets like cash, accounts receivable, inventory, and prepaid expenses, and non-current assets like property, plant, equipment, vehicles, patents, and software. If a business has cash of $80,000, receivables of $90,000, inventory of $130,000, [music] and equipment worth $200,000, total assets become $500,000.
Liabilities represent obligations. Current liabilities include accounts payable, short-term loans, taxes payable, and acred expenses due within one year. Long-term liabilities include bank loans, bonds, and lease obligations payable over several years.
If current liabilities are $150,000 and long-term loans are $200,000, total liabilities become $350,000. Equity is the residual value belonging to owners. It includes owner capital, retained earnings, and reserves.
Using the basic accounting equation, assets equal liabilities plus equity. If total assets are $500,000 and liabilities are $350,000, equity becomes $150,000. This number reflects the true net worth of the business.
One critical concept is solveny, which measures long-term survival. Solveny ratios like debt to equity ratio show how risky the capital structure is. [music] If total debt is $300,000 and equity is $150,000, the debt to equity ratio is two.
Higher ratios mean higher risk during downturns. Another important idea is asset quality. Not all assets are equally valuable.
Slowmoving inventory, old receivables or obsolete equipment inflate the balance sheet but do not provide liquidity. This is why asset turnover ratio matters. It measures how efficiently assets generate revenue.
If revenue is $1 million and total assets are $500,000, asset turnover is two. You must also understand reserves and retained earnings. Retained earnings are accumulated profits reinvested into the business.
Strong retained earnings reduce dependence on loans. Weak retained earnings increase vulnerability. Financial clarity is the first step to strategic growth.
When you understand the numbers, every decision becomes smarter, faster, and more profitable. If you want the second part of this business finance master class, then like this video. Once we hit 500 likes, we'll publish the next part with advanced business finance management and business growth opportunities.