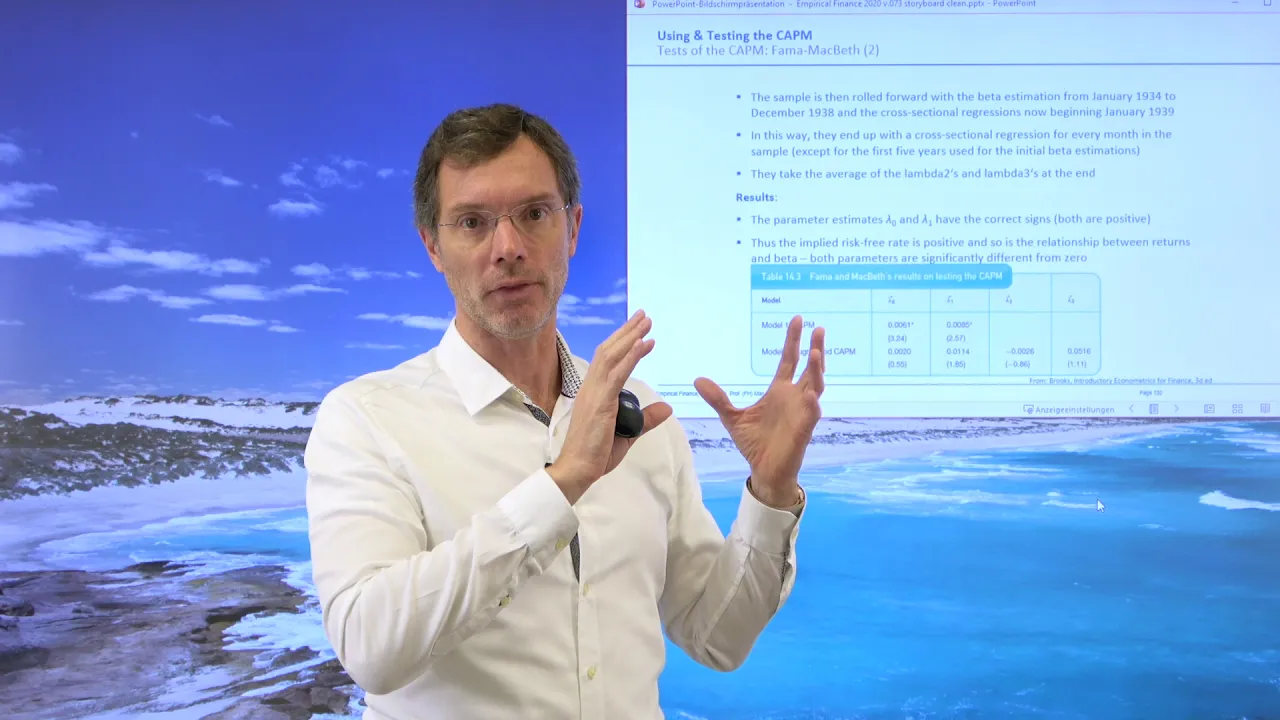
we just tested out to see whether we could replicate those findings from black jensen and scholes as to whether the sml was too flat or not so whether the risk was being priced properly versus the return so um one of the things that we implied beforehand was one of two things the first thing was that we implied that the relationship was a linear relationship if you remember so that's one thing we also now need to test whether that is the case and if you remember the second thing that we implied was that the um the
residuals the variance of the residuals um was the expected value of that was zero because our assumption was that if you have all of those residuals so the distance sum of those squared distances between each stock's returns and the and the the regression line that that for the whole market should average out and it should be zero okay so both of those things now need to be tested so what we have here is then a new regression formula and what have we got here so we've got an uh we've got the the bits that we
had before for the cross sectional array so this this is what we had beforehand the lambda 0 plus the lambda 1 times the beta now we're going to expand that a little further to include one term with the squared beta so that will test whether there is a linear or a non-linear relationship we're hoping that that turns out zero so that it's a so it continues to be to show a linear relationship and the second thing here so that's the lambda 2 and the lambda 3 that is then testing the variances of the residuals we're
also hoping that that will remain 0. so that now is our expanded cross-sectional regression line and our statistical test here again is if the cap m is true then as we just said the lambda 2 must be zero so no nonlinear effects and the lambda 3 must also be 0 no no residual variance the variance of the residuals that is other than zero so this was done in 1973 by by farmer eugene farmer and macbeth and they used a uh something to make it a little more realistic they then used this two-stage approach that we've
been discussing before but they then also used a time series of those cross-sections so not only the cross the the time series to formulate and the window and then one regression of that they used a time series of those cross-reg cross-sectional regressions to make it um more realistic so um with that rolling window there they uh then managed to get a lot of data for to try and find out what these this lambda 2 and this lambda 3 would be so what were the results from that well the initial results if you look here the
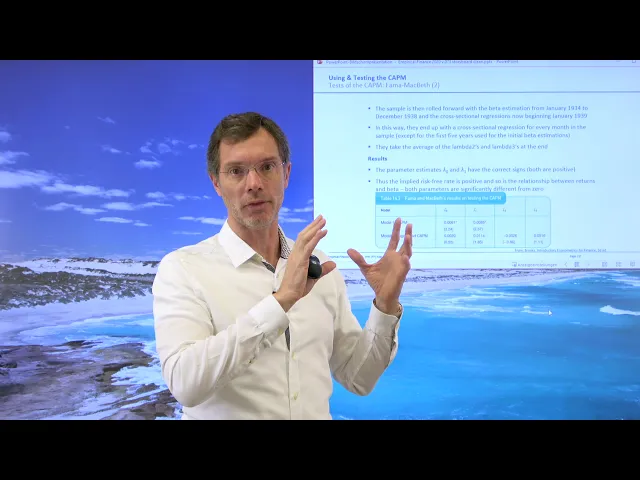
initial results were that both the lambda 0 and the lambda 1 those were the initial cross-sectional parameters that we discussed they are both positive good fortunate that would have been a bit awkward if they had not been positive um and so there um this means that the risk-free rate is or was at that period positive and that also the relationship between the beta and the returns is also positive because that is what we were hoping because our because if the sml is flat that would mean that there is zero right so at least those two
are positive and then what happens if we include all of those lambda terms that we just discussed before well then um those two first parameters become insignificant unfortunately so there's no longer significant effect that we can't say that they are so that either the risk-free rate or the slope of the sml are significantly different from zero and we do find that there is the lambda 2 and the lambda 3 are also okay from this so we have reasonable assumptions reasonable test results there but the whole test which is as you've seen quite involved throughout these
different time series and bucketings and cross-sectionals and time series of cross-sectionals has basically shown us that the cap-m is okay but not brilliant so it's showing us an isml which is not giving us the required slope that we want we can't in particularly great confidence say that the risk-free rate is actually uh greater than zero we can't actually say that the risk is being priced in all correctly from the um from the the systematic risk and not the unsystematic risk and but at least we can say that there doesn't seem to be any non-linear relationships
and also the um the the average um um variance of the uh the epsilons the the the error terms also seems to be okay so in sum we can say okay but not quite as much as we had hoped but on the other hand it is a single factor model and wanting to explain the entire universe of assets with just one factor may be a bit um exaggerated to to try to try and explain that so what does one do then it's easy to say ah cap m doesn't work when we can't say that because
it does under certain circumstances so it's easy to break something down but what do we build up in its place what are the alternatives to that and do they work any better all right so with those tests that others have done in practice let's have a look and see what that means for our portfolio so um using the portfolio that we've been using all the time up till now we will test this family macbeth extension and have a look to see with if we run those additional regressions on the beta squared to see if there
are those higher order effects in there then let's have a look and see what we get so we'll call this on the beta squared which we've calculated previously and test we've got the beta and the beta squared in there and have a look at that so what do we see we see that um there is no opportunity to reject the null hypothesis that those are zero so we've got here you see here with the beta and the beta squared we're getting uh medium high p values indicating that we then they are indistinguishable from zero so
that does mean that that is our results here and now are also consistent with the results that we just saw before that uh farmer and mcbeth found so our lambda 2 and our lambda 3 are zero which is okay that's good we're glad that there are no higher order effects that we're seeing in there but on the whole what we're seeing is that there are some decent results like this that we can confirm but um on the whole a bit inconclusive because we're confirming some of the predictions of the cap m on the individual level
but it is still not offering us a more expected return for the amount of risk that we're taking